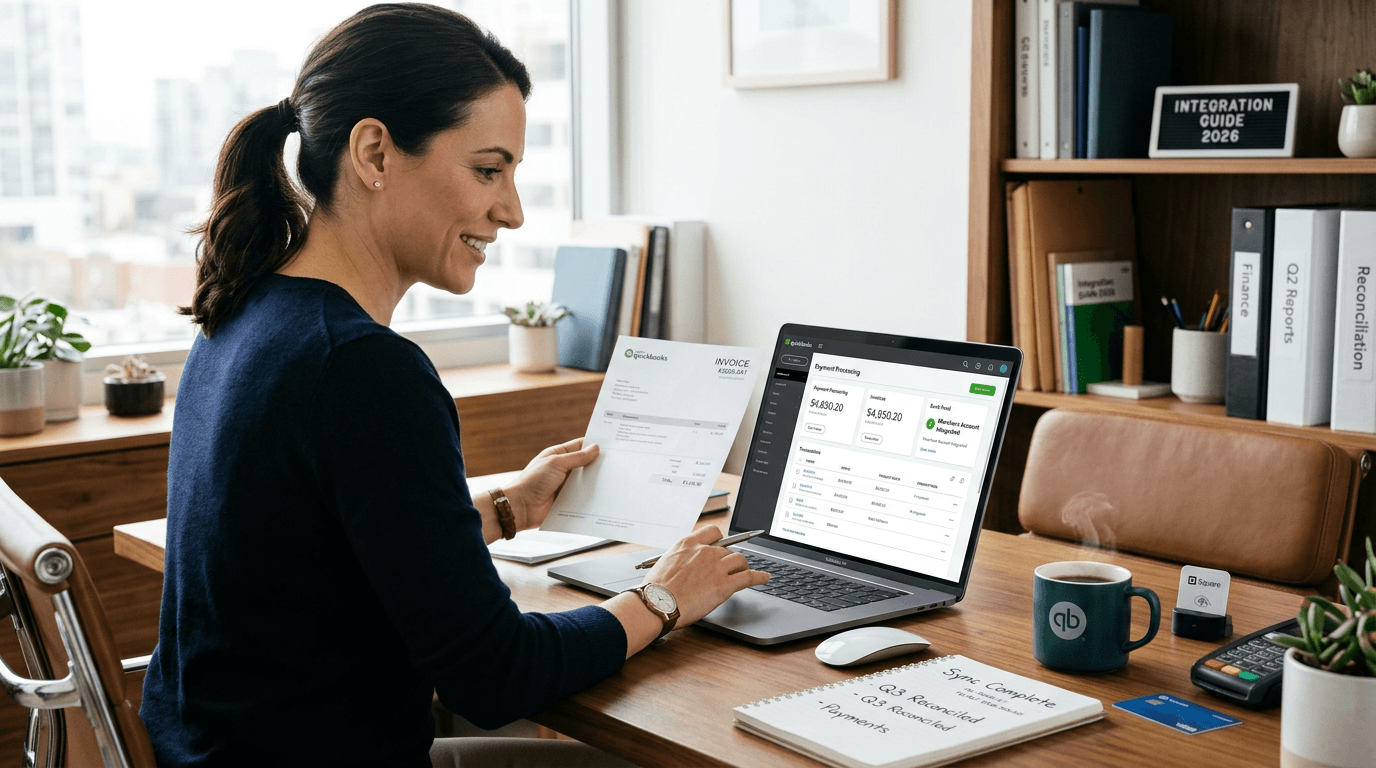
QuickBooks can be the system that combines all your invoices, customers, deposits and financial reports into one easy location. However, if your payments are processed in one place but your bookkeeping occurs elsewhere, you may find yourself chasing deposits, fees, refunds and unapplied payments.
A QuickBooks integration allows your payment processor to connect to QuickBooks so that your payments, fees, deposits, refunds and reconciliation can be automatically recorded right in your accounting software.
Why Businesses Need QuickBooks Payment Processing Integration
Because accounting accuracy requires more than simply logging that an invoice is paid, the payment needs to include information like the customer, the invoice, the payment method, the processing fee, the batch, the deposit date, and any refund or dispute information.
For many businesses, the native QuickBooks Payments solution may be the best way to keep their invoicing and accounting on one platform. However, other businesses will require a different payment processing solution with a separate merchant account or one that processes payments through an external gateway to sync with their QuickBooks software.
Why QuickBooks Payment Syncing Matters
Taking the payment is just the beginning of the process. Knowing whether the transaction settled, which invoice it was applied to, what fee it used, which bank deposit it belongs to and whether it became a refund or dispute is also necessary.
If your books do not sync with your bank, you will have to manually deal with bank deposits, fees, sales receipts, invoices and payments. The QuickBooks payment processor should make your books look better, not create another system to reconcile your books.
Who Needs This QuickBooks Payment Processing Guide
This guide is useful for businesses that use QuickBooks as their accounting hub and want payment activity to sync cleanly.
It is especially relevant for:
- service businesses sending invoices
- accounting firms, agencies and consultants
- B2B companies collecting ACH and card payments
- contractors and field service businesses
- ecommerce merchants using Shopify, WooCommerce or BigCommerce
- high-risk businesses that need a separate merchant account
- businesses comparing QuickBooks Payments with external processors
- teams using NMI, Authorize.net, Stripe, Square or PayPal with QuickBooks
- finance teams trying to reduce manual reconciliation
If your payment data touches invoices, customer records, payouts, refunds or bank deposits, QuickBooks payment processing should be planned as an accounting workflow, not just a checkout feature.
QuickBooks Payment Processing Options Compared
Different QuickBooks payment setups solve different problems. The best option depends on whether the business values native simplicity, processor flexibility, ACH control, high-risk approval or detailed reconciliation.
| Setup | Best For | Main Strength | Main Tradeoff |
|---|---|---|---|
| QuickBooks Payments | Businesses that want native invoice payments and accounting sync | Simple setup inside QuickBooks with cards, ACH, wallets and invoices | Less flexible for some higher-risk or more complex merchant account needs |
| External Merchant Account + QuickBooks Sync | Businesses that need processor choice or high-risk underwriting | More control over merchant account fit, pricing and approval | Requires integration planning and reconciliation discipline |
| NMI + QuickBooks Integration | Businesses needing gateway flexibility, ACH, invoicing and processor compatibility | Strong fit for merchants that need gateway control and accounting sync | Requires approved processing and configuration |
| Authorize.net + QuickBooks Integration | Businesses using Authorize.net with a merchant account | Familiar gateway with virtual terminal, eCheck, recurring billing and third-party sync options | QuickBooks sync usually requires a connector or third-party service |
| Stripe + QuickBooks Sync App | Supported ecommerce, SaaS and platform businesses | Strong developer tools, subscriptions and app-based QuickBooks sync | Restricted or high-risk categories may need review or another processor |
| Square + QuickBooks Sync | Retail, mobile and service businesses using Square | Good for simple POS and mobile payment workflows | Higher-risk or high-ticket businesses may need more underwriting support |
| ACH-First Setup | B2B, invoice-heavy and higher-ticket businesses | Lower card-fee dependence and better fit for large invoices | ACH authorization, returns and settlement timing must be managed |
For many businesses, the best solution is not limited to QuickBooks Payments alone. It may be QuickBooks for accounting, paired with the payment processor and gateway that best fit the business model.
Best QuickBooks Payment Processors Compared
Provider fit depends on whether the business needs native QuickBooks payments, a separate merchant account, high-risk support, ACH, gateway flexibility or a third-party sync tool.
| Provider Or Tool | Best Fit For | Key Strength | Main Tradeoff |
| Payment Nerds | Businesses that need QuickBooks payment processing, merchant account guidance, ACH, gateway strategy and high-risk support | Strong fit for QuickBooks integration planning, external merchant accounts, ACH, NMI, Authorize.net, invoicing and chargeback controls | More consultative than a native self-serve setup |
| QuickBooks Payments | Businesses that want payments built directly into QuickBooks invoices and accounting | Native invoice payments, ACH, card payments, wallets and automatic record updates | May not fit every high-risk or specialized processing need |
| NMI Bill Connect | Merchants and payment partners that want payment acceptance inside accounting software like QuickBooks or Xero | Invoice, payment and reconciliation workflow support with card and ACH tools | Requires setup through the NMI ecosystem and processing relationship |
| Authorize.net | Businesses that want a known gateway with virtual terminal, eCheck, invoicing and recurring billing | Broad gateway features and third-party QuickBooks sync options | Does not offer direct native QuickBooks sync in all workflows |
| Commerce Sync | Businesses syncing Authorize.net sales into QuickBooks | Automated bookkeeping transfer for Authorize.net transactions | Connector quality depends on workflow and accounting setup |
| PayTraQer | Businesses syncing Authorize.net, Stripe or other payment data to QuickBooks | Syncs payments, fees, refunds, taxes and transaction data | Requires configuration to avoid duplicate or misclassified entries |
| Synder | Ecommerce and multi-channel businesses syncing Stripe, PayPal, Shopify, Square and other sales channels | Useful for multiple payment and ecommerce sources feeding QuickBooks | Can be more than a simple invoice business needs |
| Stripe | Supported SaaS, ecommerce and platform businesses using QuickBooks sync apps | Strong payment platform, subscriptions, APIs and third-party accounting sync | Restricted or high-risk categories may need review or a different setup |
| Square | Retail, mobile and service businesses using QuickBooks sync workflows | Easy POS, invoices, mobile payments and app-based sync options | Less flexible for more complex high-risk merchant account structures |
Payment Nerds is usually the strongest fit when the business needs help choosing between native QuickBooks Payments, an external merchant account, NMI, Authorize.net, ACH or a high-risk payment processor. The goal is to match payment approval, accounting workflow and reconciliation needs in one plan.
How VAMP Impacts QuickBooks Payment Processing
Visa’s Visa Acquirer Monitoring Program (VAMP) is a combined program for monitoring fraud and dispute transactions for merchants using Visa. The VAMP ratio is the number of fraud reports and non-fraud disputes divided by the total number of settled Visa transactions. TC40 is the number of reports for fraud transactions, and TC15 is the number of disputes or chargebacks reported for merchants.
The Visa Acquirer Monitoring Program (VAMP) ratio is important for merchants using QuickBooks because QuickBooks maintains most of the transaction records needed to understand their customer disputes. QuickBooks can provide invoices, dates of payment received, communications sent to customers regarding refund or chargeback requests, and records of the reasons for such disputes.
VAMP also includes enumeration monitoring for merchants. Enumeration monitoring detects enumeration attacks, which are bot-driven attempts to test credit and debit cards on a merchant’s checkout or payment page. The enumeration ratio is the number of suspected enumeration attacks divided by the total number of authorization attempts on a merchant’s sales channel. VAAI stands for Visa Account Attack Intelligence and is the score for merchants exposed to enumeration attacks. Scores of 100 and above are considered above standard for merchants and put them in the excessive range, both of which result in potential fees for those merchants.
For merchants who take card-not-present payments, QuickBooks should not be the only place of observation for sales and payment processing. QuickBooks is essential for accounting and bookkeeping for merchants, but it should be supplemented with other dashboards that provide a more complete view of their payment processing and sales channels.
How to Integrate Your Merchant Account With QuickBooks
First, determine which system should be considered the source of truth for your business. For invoicing businesses, QuickBooks will create the invoice, and the payment will automatically apply to it. For ecommerce businesses, the ecommerce store will create the order, and the payment data will be sent to QuickBooks.
Next, determine which payment connection to use between QuickBooks and your merchants’ software. Options include native QuickBooks Payments, NMI Bill Connect, Authorize.net with Commerce Sync, PayTraQer, Synder, gateway export, API integration, or file-based import. Run a test with a few transactions before going live to ensure all transactions are correctly added to QuickBooks.
Finally, determine the reconciliation rules between the merchant and QuickBooks. If using QuickBooks Payments, transactions will be reflected as sales receipts. For invoices and payment applications, they can reflect invoice payments, deposits, fees, clearing account transactions, or payout transfers. Make sure to document these transactions prior to the first synchronization between your merchant software and QuickBooks to avoid spending too much time fixing duplicates after the fact.
Choosing the Right QuickBooks Integration
Ask yourself what specific payment problem you are trying to solve. Will the native QuickBooks Payments solution handle your needs? Or will you need something else with high-risk approval, ACH payments, cost-efficient processing, or greater gateway flexibility?
Consider how deeply the software integrates with QuickBooks. Does it sync customers, invoices, sales receipts, fees, refunds, deposits, classes, locations, taxes, products and chargebacks? The best QuickBooks integration will save you time and effort while maintaining accuracy in your accounting package.
Understanding QuickBooks Payment Processing Costs
QuickBooks payment processing costs include factors like card rates, ACH fees, keyed-entry rates, software fees, gateway fees, connector fees, app subscription fees, chargeback fees and bookkeeping cleanup time.
While processing rates may be lower with some payment processors than with others, the total cost of reconciliation might make another, with a slightly higher processing fee, a more cost-effective option for your business.
Common QuickBooks Integration Mistakes
The biggest mistake is syncing everything without a plan. If sales, deposits and payments come into your company from multiple systems at once, then QuickBooks will register the revenue twice, open up invoices for deposits that have already been posted and create incorrect fee records.
Another mistake is treating QuickBooks like a merchant account. QuickBooks is the accounting software and QuickBooks Payments is one payment option. You may need another merchant account and another processor to sync with QuickBooks.
QuickBooks Payment Integration Checklist
Before going live, confirm:
- which system creates the invoice or order
- which payment methods are accepted
- whether payments sync as invoice payments or sales receipts
- how processing fees are recorded
- how payouts match the bank feed
- how refunds are synced
- how chargebacks are tracked
- whether ACH returns are handled correctly
- whether sales tax, classes and locations sync properly
- whether historical transactions should be imported
- whether duplicate detection is enabled
- who has permission to process, refund or change settings
- how PCI scope and card data are handled
- how the provider supports high-risk or specialized industries
A clean test batch is worth the time. It is much easier to correct a few sample transactions than to clean up months of duplicate payment data.
Key Features of QuickBooks Payment Processing
Invoice-To-Payment Sync
An ideal payment processing integration will automatically connect payments to the invoiced product or service. The customer can pay for the product or service using a card, ACH, payment link or virtual terminal and the system will show the invoice as paid or partially paid in QuickBooks without any manual entry required by the staff. This feature is important for companies that invoice a great deal of customers. Otherwise, the accounting department will have to manually enter payments into QuickBooks.
Fee And Deposit Reconciliation
Since most payment processing companies deduct fees from the customer payment before it reaches the business bank account, linking the payment processing company to QuickBooks will allow the business to still see the fees that were deducted by the payment company. The integration should help the business accurately record gross sales, processing fees, refunds, chargebacks and deposits into QuickBooks to make reconciliation with bank feeds easier.
ACH And Card Payment Support
Businesses have a selection of payment methods to use with QuickBooks. Depending on the business type and how they want to accept payments, some businesses may want to connect their payment processing company to QuickBooks for card payments only. Other businesses may want to use ACH payments for B2B invoices. The integration should make it easy for a business to see in QuickBooks how customers paid for their products or services - whether by card, ACH, wallet, eCheck, payment link or manual entry.
Gateway And Merchant Account Compatibility
Depending on the type of business and customers they will receive payments from, they may use QuickBooks Payments or a payment gateway like NMI or Authorize.net through a merchant account to connect with QuickBooks. For high-risk merchants who may have products or services in categories that are not supported by many payment providers, the QuickBooks integration will not help with approval of payments that cannot be processed by the merchant account.
Refund, Dispute And Chargeback Records
QuickBooks should allow refunds and disputes to be tracked to the invoices from which the payments were made. The business should be able to see which payment was refunded, which invoice was refunded, which refund fee was applied for the refund and whether the customer’s payment balance was updated accordingly. For chargebacks, the refund and dispute records should also be visible to the accounting department for the business to track chargebacks and any refunds resulting from these chargebacks.
Secure Data Handling And Permissions
QuickBooks should work to reduce the amount of payment data that the business handles. Using hosted payment pages, tokenization or using secure gateways for payments will limit the amount of data that enters the business’ internal systems. Business users will have different permissions for access to QuickBooks. Only certain departments may have access to making payments and collecting payments from customers; others may only need access to view invoices in QuickBooks.
FAQs About QuickBooks Payment Processing
Q: What is QuickBooks payment processing?
A: QuickBooks payment processing allows you to accept payments from customers connected to their invoices in QuickBooks. Payments can go through either QuickBooks Payments or an external merchant account.
Q: What is a QuickBooks payment processor?
A: A QuickBooks payment processor is the provider of payments to businesses that also connect to QuickBooks accounting software. This could be QuickBooks Payments or an external provider.
Q: What does QuickBooks integration mean for payments?
A: QuickBooks integration means that payments will be synced with the accounting software. Depending on the selected payment processing company and software, integration can sync sales and payment information with invoices, customers, fees, refunds, deposits, taxes, classes, locations and accounting software bank feeds.
Q: Can I use my own merchant account with QuickBooks?
A: In most cases, yes. Any business can use its own merchant account or payment gateway with QuickBooks through integration software. The best payment processing and accounting software for a business can be determined during an initial consultation with a payment processing company.
Q: Does Authorize.net integrate with QuickBooks?
A: Authorize.net does integrate with QuickBooks through third-party services such as Commerce Sync, PayTraQer or other integration services. Authorize.net does not offer direct integration with QuickBooks for every process.
Q: Can NMI work with QuickBooks?
A: NMI offers tools like Bill Connect that allow them to work with QuickBooks and its associated software to manage payments from customers.
Q: Is QuickBooks Payments enough for high-risk merchants?
A: QuickBooks Payments works for many high-risk merchants. However, some may need their own merchant account to manage the increased risks associated with their products or services. A review of the merchant account and the products sold is necessary before choosing any software or providers.
Q: Can Payment Nerds help with QuickBooks integration?
A: Payment Nerds can compare QuickBooks payment processing, QuickBooks integration, ACH payments, NMI, Authorize.net, merchant accounts, high-risk merchants and more.
Conclusion
A good QuickBooks payment setup should make accounting easier for your business. With the proper integration between your payments provider and QuickBooks, you’ll have all the data you need to trust the accounting software.
Payment Nerds can help you compare QuickBooks payment processing companies, QuickBooks integrations, ACH payments, gateways, merchant and high-risk payment processors. In the end, you want to find a provider that keeps your payments going while also keeping your QuickBooks software running smoothly.
Sources
- QuickBooks. “Accept Payments Online and In-Store.” Accessed June 2026.
- QuickBooks. “Credit Card Processing Fees & Rates Explained.” Accessed June 2026.
- QuickBooks Support. “QuickBooks Payments Fees: Credit Card Processing and Transaction Rates.” Accessed June 2026.
- NMI. “Bill Connect Integration.” Accessed June 2026.
- Authorize.net. “Credit Card Payment Processor, Online Payments Systems and Processing.” Accessed June 2026.
- Authorize.net Support. “Does Authorize.net Work With QuickBooks?” Accessed June 2026.
- QuickBooks App Store. “Authorize.Net by Commerce Sync.” Accessed June 2026.
- QuickBooks App Store. “Synder.” Accessed June 2026.
- PayTraQer. “Authorize.Net QuickBooks Integration.” Accessed June 2026.
- Visa. “Visa Acquirer Monitoring Program Fact Sheet.” Accessed June 2026.