
A customer wants to pay for an invoice, reserve a service, or order something. Instead of asking the customer to go to a checkout page, the employee can enter the payment information into a secure virtual terminal to process the transaction. That’s what is known as credit card processing by phone through a virtual terminal.
Virtual terminals are helpful for businesses that do not have their customers standing at a register, such as professional services companies. However, virtual terminals do involve some risk, since transactions manually entered by an employee are card-not-present transactions that cost more and can be more difficult to defend in the event of a customer dispute.
How Virtual Terminal Credit Card Processing Works
A virtual terminal allows a computer, tablet, or phone to function as a payment terminal through a web browser. The employee will receive the payment details from the customer and manually enter the card number, expiration date, security code, and other billing information.
The gateway will then send the transaction to the merchant’s processor for authorization.
Businesses can process credit cards by phone for sales such as:
- service deposits
- reservations
- wholesale orders
- invoice payments
- mail and telephone orders
- recurring customers purchases
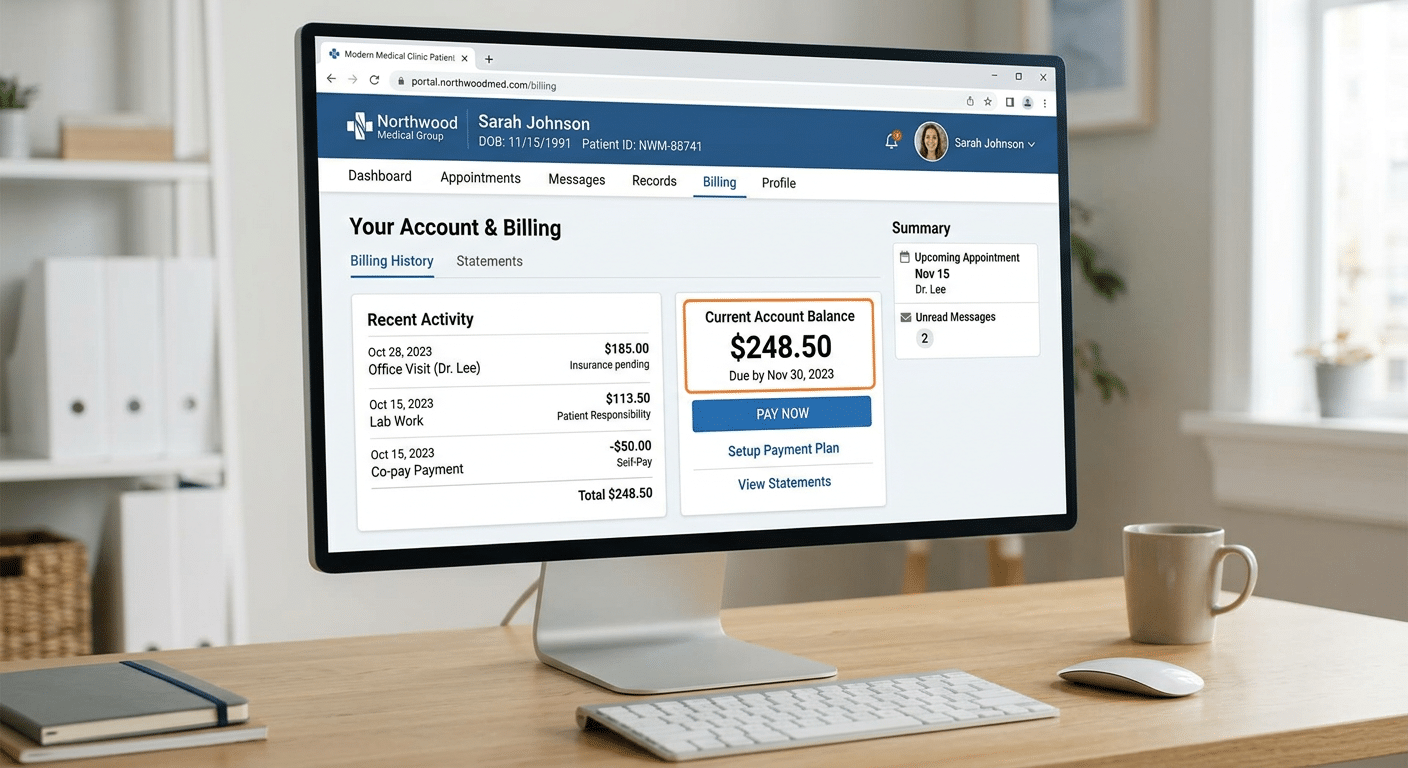
- health care and other service company balances
- large business orders
- emergency orders
NMI’s Virtual Terminal can process sales, authorizations, captures, voids, and refunds. The system also allows for the processing of electronic checks if the merchant’s account supports such transactions.
Authorize.net allows businesses to create a virtual terminal with the software to accept payments over the phone or through mail orders without the need for card terminal hardware. Authorize.net’s systems also allow businesses to accept credit cards over the phone or online with eCheck, recurring billing, and electronic invoices.
Since no physical card is present during the transaction, it’s important for merchants to collect certain information from customers. This information can then be used to verify the customer’s payment authorization. Information such as AVS, CVV, receipts, and other details that describe the customer’s account can be crucial when using virtual terminal software.
7 Best Virtual Terminals for Phone Payments in 2026
The best virtual terminal depends on transaction volume, industry, risk profile and whether the business needs only keyed payments or a broader gateway and merchant-account setup.
| Virtual Terminal | Best Fit | Pricing Approach | Main Consideration |
|---|---|---|---|
| Payment Nerds + NMI | High-risk and specialized MOTO merchants | Merchant-specific | Requires an approved merchant account |
| Authorize.net | Businesses wanting gateway flexibility and ACH | Published all-in-one plan available | High-risk approval depends on underlying processor |
| Square | Straightforward lower-risk small businesses | Flat-rate keyed pricing | Limited fit for many high-risk industries |
| PayPal | Businesses already operating in the PayPal ecosystem | Flat-rate Virtual Terminal pricing | Virtual Terminal transactions lack Seller Protection |
| Clover | Businesses mixing POS and phone orders | Keyed rate based on plan/agreement | Contract and pricing can vary by provider |
| Helcim | Eligible businesses wanting interchange-plus pricing | Interchange plus markup | Industry eligibility matters |
| Stax Pay | Higher-volume professional-service businesses | Subscription + interchange | Monthly subscription makes more sense at sufficient volume |
1. Payment Nerds + NMI: Best for High-Risk Phone Payments
If your business requires specialized underwriting, the Payment Nerds merchant account can give you more flexibility than a self-service virtual terminal offers.
NMI’s keyed transactions allow employees with specific permissions to add sales, authorizations, and refunds to the merchant’s total. The company’s platform also integrates with remote sales and recurring billing software, customer vaulting, and ACH transactions.
The Payment Nerds and NMI combination provides flexibility with the virtual terminal and an acquiring company that understands your business model.
Best for: High-risk, MOTO, B2B and specialized businesses
2. Authorize.net: Best for Gateway Versatility and ACH
Authorize.net offers one of the most established virtual terminal solutions for businesses that take phone and mail orders, as well as those with e-commerce, invoicing, and recurring payment needs.
Authorize.net’s all-in-one solution starts at $25 per month plus 2.9% and 30 cents per transaction (eligibility subject to approval). If merchants already have a merchant account with Authorize.net, they can also use its gateway-focused solution instead.
Authorize.net is a good option for businesses that require both card and eCheck processing through their gateway.
Best for: B2B, professional services, and merchants in eligible high-risk categories.
3. Square Virtual Terminal: Best for Simple Phone Payments
Square offers one of the simplest virtual terminals for businesses that want to avoid complexity.
Square’s virtual terminal has no separate monthly charge. However, transactions manually entered into the system are subject to a fee of 3.5% plus 15 cents—the same rate that Square publishes for its U.S. merchants. Businesses can enter a card number directly into the Square virtual terminal, use cards on file at the business, or even create a link that directs customers to a payment screen.
Square does note, however, that manually entered transactions are associated with a greater risk of fraudulent use. Any chargebacks resulting from those manually entered transactions are more difficult for the business to contest.
Finally, Square will not allow certain types of merchants to use the virtual terminal. Businesses in categories that are unusually restricted or high-risk, for instance, will need to establish a separate merchant account with Square to receive the necessary high-risk underwriting approvals.
Best for: Small businesses with lower risk who do not want to pay a virtual terminal subscription fee.
4. PayPal Virtual Terminal: Best for Existing PayPal Businesses
PayPal Virtual Terminal lets approved businesses enter credit and debit card transactions directly into their browser. Customers do not need a PayPal account.
PayPal charges 3.39% plus 29 cents per Virtual Terminal transaction, with no monthly fee for U.S. businesses.
PayPal does not include Virtual Terminal transactions in its Seller Protection program.
Best for: Business owners who already use PayPal.
5. Clover Virtual Terminal: Best for POS and Phone Orders Together
Clover Virtual Terminal: available through the Clover Web Dashboard, the virtual terminal can take and process payments and refunds from a computer, smartphone, or tablet.
There is no additional cost for the virtual terminal; however, the transactions will use the merchant’s keyed-in rate. Clover states that the rate will depend on the merchant’s processing company and the service agreement between the two entities.
As such, the virtual terminal is of more use to those who use Clover POS systems to take payments in person, but also who must take cash deposits, mail orders, or phone payments from customers.
Best for: Retail and service businesses that use or plan to use a Clover POS system.
6. Helcim Virtual Terminal: Best for Interchange-Plus Pricing
Helcim combines its Virtual Terminal with invoicing, recurring billing, payment links, customer vaulting, and ACH.
Its current U.S. pricing model uses interchange plus a processor margin. For businesses processing up to $50,000 per month, Helcim uses interchange plus a markup of 0.50% and 25 cents. Lower markups apply to higher monthly volumes. There is no separate fee for the Virtual Terminal.
While the interchange-plus model is generally more expensive than a flat-rate payment platform, it can be attractive to merchants who are eligible for such pricing and who desire greater transparency in their cost structure.
Best for: Established businesses that want to see interchange-plus pricing with their invoicing solution.
7. Stax Pay: Best for Higher-Volume Professional Services
Stax Pay uses a subscription model rather than adding a percentage to the interchange value.
The plans start at $99 per month for businesses that process up to $150,000 per year. Card-not-present transactions are priced at interchange plus a flat fee of 15 cents. Higher annual processing volumes are associated with higher subscription plan costs.
The platform offers virtual payments, invoicing, recurring billing, payment links, and reporting.
Stax Pay may be more cost-effective for merchants who process a high volume of payments each year; the higher the expected volume, the more likely the subscription model is to be cost-effective compared to a percentage-based model.
Best for: Professional and service businesses that process a high volume of payments annually.
Compare Cost, Security and Merchant-Account Fit
Do not choose a virtual terminal based solely on transaction rate. A business that takes two $500 deposits per week will have a different virtual terminal requirement than a call center that takes hundreds of transactions daily.
Review the following factors prior to making your selection:
- keyed transaction pricing
- gateway fees
- monthly platform fees
- merchant-account terms
- industry eligibility
- maximum transaction size
- monthly transaction volume
- ACH transactions support
- recurring billing support
- customer vaulting support
- employee permissions
- AVS and CVV permissions
- refund permissions
- accounting integration support
- reporting tools
- chargeback tools
If you operate a high-risk business, determine merchant-account eligibility before you select a virtual terminal. A sleek virtual terminal is useless to you if the merchant account does not support your industry.
Use Payment Links When Manual Entry Is Unnecessary
A virtual terminal is helpful for taking payment information over the phone. It should not be the first option every time a merchant takes a sale over the phone.
Using secure invoice and payment links allows customers to enter their payment information themselves. This avoids the manual entry of payment information and provides merchants with a more detailed authorization record for their transactions.
A business may therefore use:
- virtual terminal for phone orders
- payment links for remote customers
- invoices for B2B payments
- ACH for larger bills
- recurring billing for card on file sales
The best payment stack will provide several of these options instead of forcing the business to manually enter the card information for sales taken over the phone.
Control VAMP Risk on Phone Payments
Since phone transactions are card-not-present transactions, merchants should be watching for fraud and disputes – especially as MOTO transactions increase in volume.
Visa’s Acquirer Monitoring Program (VAMP) monitors fraud and disputes to identify instances of enumeration or automated systems attempting to identify stolen card data. Visa establishes a minimum count of 1,500 records for fraud and disputes to identify VAMP activity, but acquirers or payment processors can act well before this threshold is reached.
Visa reported in March 2026 that nearly half of the acquirers identified as having high rates of transaction problems had improved within one quarter. The VAMP ratio for these acquirers fell 45% from one quarter to the next.
Merchants who take orders over the phone should pay close attention to the following transaction metrics:
- repeated declined transactions
- unusual ticket sizes
- multiple cards used by the same customer
- billing information that does not match the customer
- high rates of requiring refunds
- disputed transactions
- spikes in transaction counts
- unusual activities by employees taking orders over the phone
Virtual Terminal Mistakes Merchants Make
Common problems include:
- Keying in cards instead of using secure payment links
- Failing to get billing information
- Writing card numbers on paper
- Storing card details in spreadsheets and CRM software
- Allowing all employees to issue refunds
- Using vague billing information
- Creating tickets valued higher than allowed limits
- Failing to document telephone authorizations
- Repeatedly retrying declined cards
- Ignoring results from AVS and CVV
- Choosing virtual terminal without confirming business eligibility
- Thinking keyed in cards will cost the same as in-person payments
- Ignoring employee transactions
- Waiting for warnings from payment processor before reviewing VAMP report
Never retain CVV after authorization. CVV is classified as sensitive data by PCI DSS and cannot be stored after authorization.
Virtual Terminal and Phone Payment Questions
Q: What is a virtual terminal?
A: A virtual terminal is a secure website that allows a merchant to manually enter credit card data without the use of a credit card terminal.
Q: How can I process credit cards by phone?
A: By entering the credit card information provided over the phone into the merchant’s virtual terminal.
Q: Is processing credit cards by phone more expensive?
A: It often is. Since there is no physical credit card to authenticate the cardholder, there is an additional cost per transaction.
Q: What is the best virtual terminal for high-risk merchants?
A: The virtual terminal options of NMI or Authorize.net, provided that the merchants have an appropriately underwritten merchant account, will provide more flexibility to those with high-risk businesses. Payment Nerds works with these two options for MOTO and other high-risk virtual terminals.
Q: Which virtual terminal has no monthly fee?
A: Square, PayPal, and Helcim advertise that they do not require merchants to pay a monthly fee to utilize their virtual terminals. However, standard processing fees will apply.
Q: Can a virtual terminal accept ACH?
A: Some virtual terminals do accept ACH transactions. NMI, Authorize.net, Helcim, and Stax allow merchants to accept bank payments in addition to credit card payments.
Q: Is it safe to take credit card numbers over the phone?
A: As long as the merchant accurately enters the credit card information into a secure virtual terminal and follows the data security procedures outlined by the PCI DSS standards, taking credit card orders over the phone is safe. Writing down credit card numbers is not recommended.
Q: Should I use a virtual terminal or a payment link?
A: Use a virtual terminal if an employee will take the order and process the payment over the phone or by mail. Use a payment link if the customer will enter their payment information on your site.
Q: Does VAMP apply to virtual terminal transactions?
A: Any instances of fraud with Visa card-not-present transactions will contribute to VAMP statistics. This includes virtual terminal transactions, MOTO orders, and other card-not-present sales.
Pick the Virtual Terminal That Fits the Merchant Account
Square and PayPal make credit card processing by phone easy for small, straightforward merchants. Clover works well for merchants already using Clover’s POS systems, and Helcim and Stax offer alternative pricing structures for qualifying merchants.
For high-risk, B2B, and other more complicated merchants in the MOTO space, it’s better to start with the acquiring company relationship rather than the virtual terminal software. While NMI and Authorize.net offer the flexibility of virtual terminal software, the merchant account underpinning those vendors will determine whether your business and transaction model are supported.
Sources
- NMI. “Credit Card Processing Virtual Terminal Guide.” Accessed August 2026.
- Authorize.net. “Accept Credit Card Payments Online, In-Person and by Phone.” Accessed August 2026.
- Square. “Virtual Terminal Credit Card Processing.” Accessed August 2026.
- PayPal. “Virtual Terminal.” Accessed August 2026.
- Clover. “Virtual Terminal Payment Processing.” Accessed August 2026.
- Helcim. “Payment Processing Pricing.” Accessed August 2026.
- Stax. “Payment Processing Pricing.” Accessed August 2026.
- Visa. “Evolving the Visa Acquirer Monitoring Program.” Accessed August 2026.